September 23, 2026

HSA and Medicare: How to Avoid a Costly Contribution Mistake

How Medicare Enrollment Can Create Consequences for Your HSA Contributions


Many Americans spend years building savings in a Health Savings Account (HSA), one of the most tax-advantaged ways to save for health care expenses. HSA funds can be used for many qualified medical expenses, including deductibles, copays, coinsurance, prescription medications and certain medical equipment… even when you are on Medicare. That is why HSAs can be such an important part of your retirement planning.


But when Medicare enters the picture, the rules can lead to unexpected tax consequences.


Where Medicare Can Create a Problem with HSAs


Some people continue working after age 65 and remain covered by an employer-sponsored HSA-eligible high-deductible health plan (HDHP). That's allowed. Simply turning 65 or becoming eligible for Medicare doesn't automatically prevent you from contributing to an HSA. The issue begins when you are actually enrolled in Medicare. Once you're enrolled in Medicare Part A and/or B, you generally can no longer contribute to an HSA.


The confusion is that Medicare enrollment doesn't always happen when people expect it to.


One way this can happen is through Social Security benefits. If you're already receiving Social Security benefits when you become eligible for Medicare, you're generally automatically enrolled in Medicare Part A and Part B. While Part B can generally be declined, premium-free Part A usually takes effect automatically. Once Part A coverage begins, you're no longer eligible to contribute to an HSA, even if you're still working and covered by your employer's HSA-eligible health plan.


That means someone could continue making HSA contributions through payroll, or continue receiving employer contributions, without realizing that Medicare coverage has kicked in and made them ineligible to make those contributions.


A second issue can arise when someone delays Medicare while continuing to work and contribute to an HSA. When that person later applies for premium-free Medicare Part A after age 65, their Part A coverage can generally be retroactive for up to six months, but not earlier than the month they first became eligible for Medicare.


This creates a potential HSA problem because a person can't make HSA contributions for months in which they're covered by Medicare. If Part A is applied retroactively, HSA contributions made for those retroactively covered months may become excess contributions, even though the person wasn't aware at the time that Medicare coverage would later reach back to those months.


For example, someone who works past 65, keeps an HSA-eligible employer plan and delays Medicare might continue contributing to an HSA. If they later enroll in Medicare and receive six months of retroactive Part A coverage, some of those recent HSA contributions may no longer be allowable.


That's why it's important for people who work past 65 to coordinate the timing of Medicare enrollment, Social Security benefits, and HSA contributions.


The Potential Tax Consequences


The IRS generally imposes a 6% excise tax on these “excess” HSA contributions that aren't corrected as permitted under IRS rules. The tax can apply for each tax year the excess remains in the account.


In some cases, an individual may be able to avoid the 6% excise tax by withdrawing the excess contribution, along with any earnings attributable to it, by the applicable tax-return deadline and properly reporting the correction.


Because the tax treatment depends on the circumstances and timing, anyone who discovers a possible excess contribution should consider contacting the HSA custodian and a qualified tax professional.


How to Avoid HSA Contribution Problems


If you're approaching Medicare eligibility, planning to enroll in Medicare, or applying for Social Security benefits after age 65, review your HSA contribution strategy ahead of time. The correct time to stop contributing isn't the same for everyone.


For example, if you enroll in Medicare during your Initial Enrollment Period, you generally need to make your last HSA contribution for the month before your Medicare Part A coverage begins. Special rules can apply if your birthday is on the first day of a month.


If you delay Medicare and later enroll in premium-free Part A, Medicare recommends accounting for the possibility that Part A coverage will be retroactive. If you enroll six or more months after turning 65, that generally means stopping HSA contributions six months before the month you apply for Medicare or Social Security benefits.


Because enrollment dates and individual circumstances can vary, confirm the effective date of your Medicare coverage before determining your final HSA contribution.


Your HSA Can Still Be Valuable After Medicare


Enrolling in Medicare means you can no longer make HSA contributions, but it doesn't mean you can't use the money already in your account. You can continue pulling from your HSA after enrolling in Medicare, and withdrawals for qualified medical expenses can generally remain tax-free. HSA funds can therefore continue to be a valuable resource for health care expenses throughout retirement.


The key is planning ahead. Understanding when Medicare coverage begins, and when HSA contributions must stop, can help you preserve the tax advantages you've worked to build.

Prescription pill bottle and injectable pen on a table with a doctor's notes
By No author September 16, 2026
The Medicare GLP-1 Bridge program offers certain eligible people access to select weight-management drugs for a $50 copay. Learn what's covered and who may qualify.
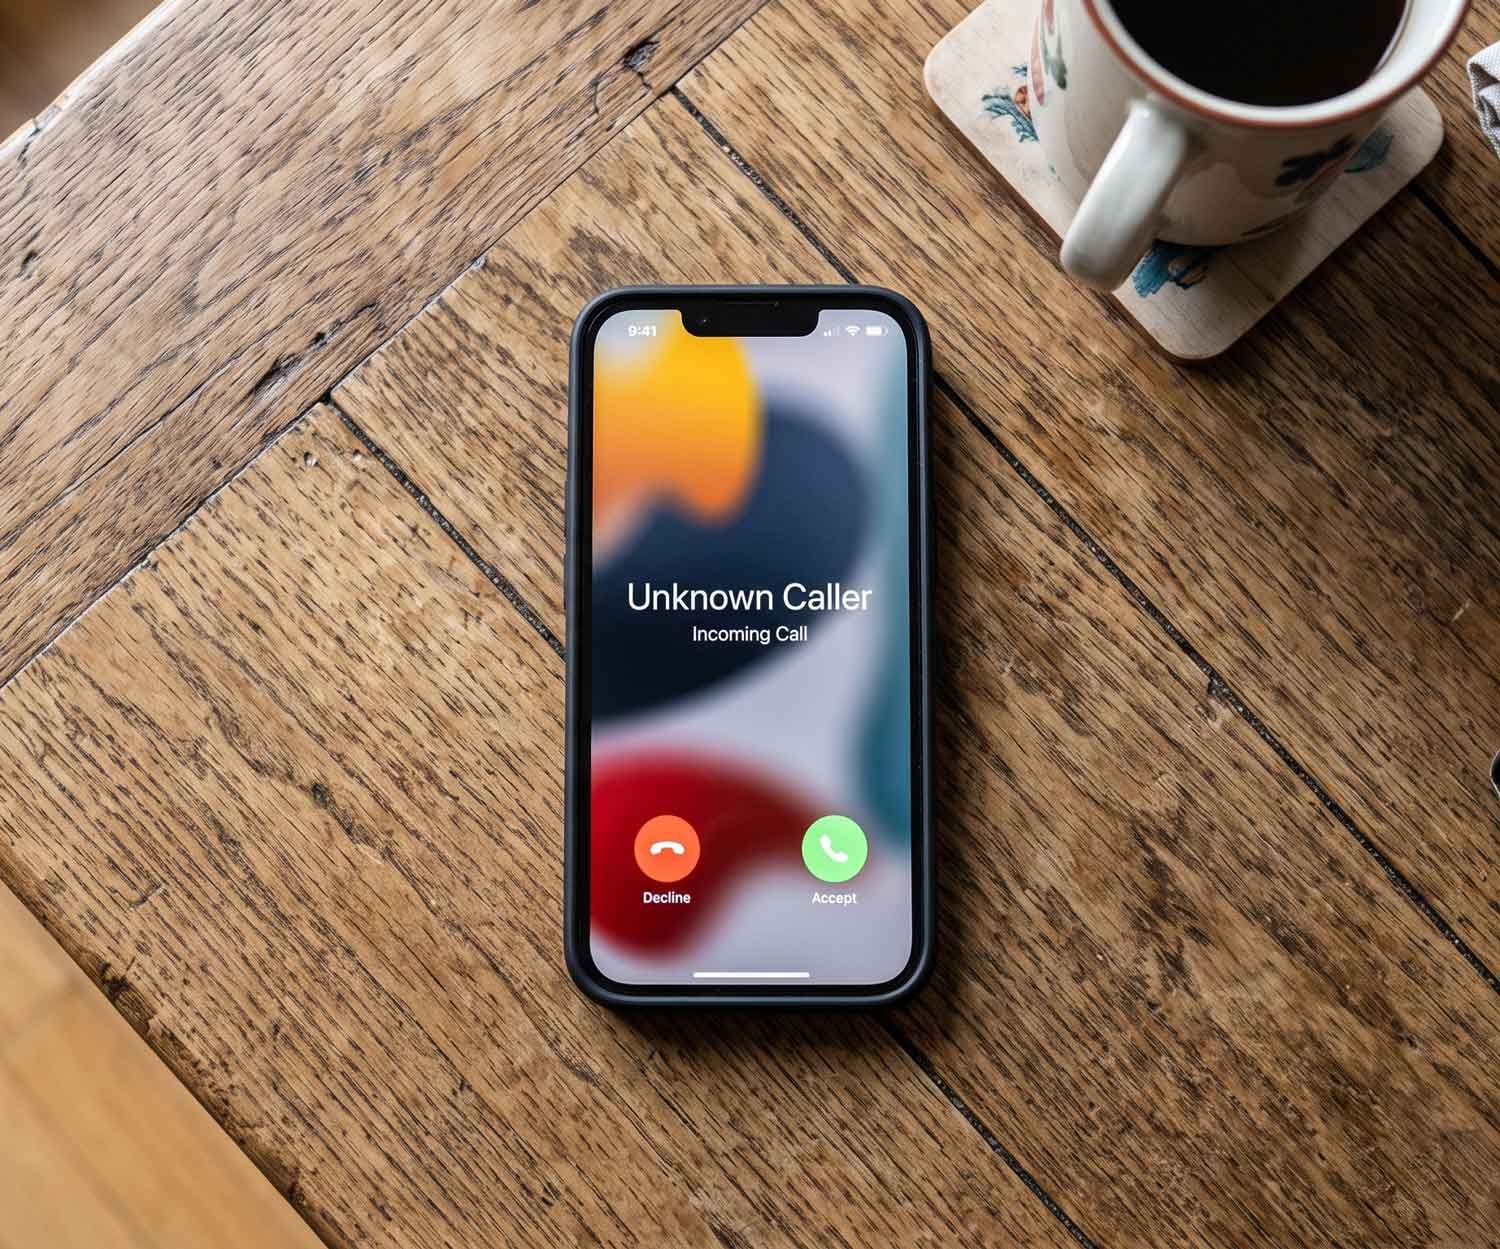
Senior looking at a smartphone showing an incoming call from an unknown number
By No author September 9, 2026
Medicare scam calls and fake insurance agents are on the rise. Learn the warning signs, how to verify who you're talking to, and what to do if you share information.
Older person's hands typing on a laptop keyboard indoors
By No author September 2, 2026
Annual Enrollment for Medicare runs October 15 – December 7, 2026. Here's what to know about comparing plans, key dates, and how to get ready.
Smart home devices: robot vacuum, voice speaker, smart button, and emergency pendant in a hallway.
July 16, 2026
See how smart lighting, robot vacuums, stove shut-offs, medication reminders, and fall monitors can help seniors at home, plus what Medicare and Medigap do and do not cover.
Smiling person in a white hat outdoors, with a hand raised near the brim.
July 16, 2026
Learn what Medicare covers for skin cancer screenings, dermatologist visits, biopsies, and treatment, plus tips for prevention and early detection.
Two blue aluminum drink cans viewed from above, with water droplets on the lids.
By Agency Bloc September 24, 2025
As the summer sun beckons and thirst levels rise, it's tempting to reach for a cold, fizzy beverage. But before you pop open that soda can, consider this: your drink choice has long-term implications for your health. The Hidden Risks in Your Glass A comprehensive study by the International Agency for Research on Cancer (IARC) analyzed data from over 451,000 individuals across 10 European countries over a 16-year period. The findings revealed that consuming two or more 250 ml glasses of soft drinks daily—whether sugar-sweetened or artificially sweetened—was associated with a higher risk of all-cause mortality compared to those who drank less than one glass per month. Delving deeper: Artificially Sweetened Beverages : Individuals consuming two or more glasses daily had a 26% higher risk of death compared to those who consumed less than one glass per month. Specifically, there was a 52% increased risk of death from circulatory diseases. Sugar-Sweetened Beverages : Those consuming one or more glasses daily faced a 59% higher risk of death from digestive diseases. All Soft Drinks : A notable association was found between soft drink consumption and increased mortality from Parkinson's disease. Alternatives That Aren’t Any Healthier Think fruit juice or energy drinks are a safer bet? A study involving 13,440 U.S. adults aged 45 and older found that each additional 12-ounce serving of sugary beverages, including 100% fruit juice, was linked to an 11% higher risk of all-cause mortality. Specifically, each additional 12-ounce serving of fruit juice was associated with a 24% increased risk. Watch the sugar content of iced coffee beverages and alcoholic cocktails as well. Lifestyle Factors Matter, Too It's essential to note that high soft drink consumption often correlates with other unhealthy lifestyle choices. The IARC study observed that individuals who drank more soft drinks typically had higher body mass indexes and were more likely to smoke. Even after adjusting for factors like diet, physical activity, smoking, and education, the association between soft drink consumption and increased mortality risk remained significant. Refreshing Alternatives for the Season Looking to quench your thirst without compromising your health? Here are some delightful, healthier options: Infused Water : Add slices of citrus fruits, cucumbers, or berries to your water for a refreshing twist. Herbal Iced Teas : Brew teas like hibiscus or mint, chill them, and enjoy over ice. Sparkling Water with a Splash : Mix sparkling water with a splash of 100% fruit juice for a fizzy treat. Homemade Lemonade : Use fresh lemons, water, and a touch of natural sweetener like honey or stevia. Coconut Water : A natural source of electrolytes, perfect for rehydration. Final Thoughts Summer is a time for relaxation and enjoyment. By making informed beverage choices, you can savor the season while prioritizing your health. So, the next time you're reaching for a drink to beat the heat, consider these healthier alternatives. Your body will thank you!
SHOW MORE