September 16, 2026

What Medicare Really Covers for GLP-1 Drugs in 2026

A Plain-English Guide to the New $50 Copay Program and How to Get Started


For years, Medicare generally has not covered medications when they are prescribed solely for weight loss. Federal law currently excludes drugs used for weight loss from the standard Part D benefit. However, a new, limited exception to the rule became available on July 1, 2026.


Through a temporary program called the Medicare GLP-1 Bridge program, certain people with Medicare drug coverage may now be able to get select GLP-1 medications intended for weight management for a $50 copay per one-month supply. The Bridge program does not eliminate the underlying Part D exclusion for weight-loss drugs. Instead, it provides a separate, temporary pathway for eligible Medicare beneficiaries.


Read on to learn what the program covers, who could qualify, and how the process works.


Medicare Part D’s Existing GLP-1 Coverage


Before looking at the new Bridge program, it helps to understand GLP-1 coverage up to this point.


Medicare Part D can cover certain GLP-1 medications when they are prescribed for a medically accepted condition other than weight loss. Depending on the particular drug, those conditions may include:


• Type 2 diabetes

• Certain cardiovascular risks

• Moderate-to-severe obstructive sleep apnea

• Certain cases of metabolic dysfunction-associated steatohepatitis (MASH), a serious form of fatty liver disease


If your doctor prescribes a GLP-1 for one of these approved conditions, or something other than weight loss, your Medicare Part D plan may cover it. Which specific drugs are covered and what requirements apply depend on your particular plan.


The New Medicare GLP-1 Bridge Program


The Medicare GLP-1 Bridge program is a temporary program scheduled to run from July 1, 2026, through December 31, 2027. It gives eligible people with Medicare drug coverage access to certain GLP-1 medications for the purpose of weight management for a flat $50 copay per one-month supply. The program is available nationwide, including in U.S. territories.


One important note is that the Bridge program operates outside the regular Part D benefit. Medicare pays participating pharmacies through a central processor rather than having your Part D plan pay for the medication. This means your Part D plan does not have to opt into the Bridge program for you to participate.


Which Drugs Are Covered as of August 2026?


As of August 2026, the Medicare GLP-1 Bridge includes these medications when prescribed to reduce excess body weight and maintain weight reduction:


• Foundayo — tablet

• Wegovy — injection or tablet

• Zepbound — KwikPen only (not single-dose vials or pens)


Because the Bridge program is evolving, Medicare may update covered products over the duration of the program.


What About Ozempic and Mounjaro?


The names of these medications are familiar to many people, so you may wonder if they're covered. The answer is no: Ozempic and Mounjaro are not covered through the Medicare GLP-1 Bridge program. Instead, they remain subject to regular Medicare Part D coverage rules and are most often prescribed to treat type 2 diabetes. Wegovy and Zepbound, on the other hand, are versions approved specifically for chronic weight management.


So, if you take a GLP-1 medication for a condition that can be covered under Part D, continue working with your health care provider and Medicare drug plan or Medicare Advantage plan regarding coverage. If, however, you are seeking a pathway to weight management, then the Bridge program may be worth pursuing. The first step is to find out if you're eligible.


Who Qualifies for the GLP-1 Bridge?


To participate, you must be 18 or older, have Medicare drug coverage, and meet one of Medicare's clinical eligibility standards when starting treatment.


You may qualify if you have:


• A body mass index (BMI) of 35 or higher

• A BMI of 30 or higher plus heart failure with preserved ejection fraction, uncontrolled high blood pressure, or chronic kidney disease at stage 3a or higher

• A BMI of 27 or higher plus prediabetes, a previous heart attack or stroke, or symptomatic peripheral artery disease


You may also qualify for coverage of a GLP-1 drug if you started taking a GLP-1 drug prior to the start of the Bridge program and you met the eligibility conditions when you started taking the drug, even though you may not qualify now. For example, if you started taking a GLP-1 drug in January 2025 and at that time your BMI was 35, you may qualify for the Bridge program even if your current BMI is 25.


Medicare has additional clinical definitions and requirements for these conditions. Your health care provider will determine whether you meet the program's criteria.


You generally aren't eligible for the Bridge program if you already get GLP-1 drugs through your Part D coverage or if you have certain conditions for which GLP-1 treatment may be covered through regular Part D rules, including:


• Type 2 diabetes

• Moderate-to-severe obstructive sleep apnea

• Certain fatty liver disease


Having one of these conditions may make you ineligible for the Bridge program even if your particular Medicare drug plan doesn't currently cover the medication. In that situation, regular Part D coverage and exception rules may apply.


You must also have qualifying Medicare drug coverage. That can include:


• A standalone Medicare Part D plan

• A Medicare Advantage plan with drug coverage

• A Special Needs Plan with drug coverage

• Certain employer or union Medicare drug plans

• The LI NET program


How Do You Get Started?


The process starts with your health care provider rather than your Medicare drug plan.


• Talk with your health care provider. Ask whether one of the covered medications is medically appropriate for you and whether you meet Medicare's BMI and health-condition requirements.

• If they agree, your provider will send a prescription to your pharmacy. The medication must be prescribed as part of a treatment plan that includes diet and physical activity.

• The first fill may take extra time. The pharmacy's initial claim may trigger a prior-authorization request to your provider. Once the required prior authorization is submitted, CMS says an approval or denial will generally be communicated within 72 hours.

• Watch for a letter from Medicare. If your prior authorization is approved, Medicare will send you a letter confirming coverage through the Bridge program.

• Be prepared to provide your Medicare information at the pharmacy. Your pharmacy may need your Medicare Number or, in some circumstances, the last four digits of your Social Security Number to process the claim.


Once approved, the prior authorization generally remains valid through December 31, 2027, including for refills and dose changes. A new authorization may be required if you change to a different GLP-1 medication covered by the Bridge.


How Does the $50 Copay Work?


The $50 copay works differently from what you normally pay for medications covered by your Part D plan because Bridge program medications are paid for outside your regular Part D benefit.


For medications you receive through the Bridge program:


• You pay a flat $50 copay for a one-month supply

• The $50 does not count toward your Part D deductible or annual out-of-pocket limit

• It will not appear on your Part D Explanation of Benefits or your Medicare Summary Notice

• Extra Help does not reduce the $50 copay

• The Medicare Prescription Payment Plan cannot be used to spread the $50 cost across monthly payments


Those differences are especially important to understand if you receive Extra Help or are tracking your prescription drug spending toward your Part D out-of-pocket limit.


Your Next Step


If you think you might qualify for the Medicare GLP-1 Bridge, start by talking with your health care provider. Your provider can help determine whether one of the covered medications is appropriate for you and whether you meet Medicare's eligibility requirements.


The GLP-1 Bridge is currently scheduled to end December 31, 2027, so it's also worth discussing how your treatment and coverage options could change after the program period ends.


If you have questions about your current Medicare drug coverage, we're happy to help you understand how your plan works and where the GLP-1 Bridge program may fit in.


This article is accurate as of August 2026. The GLP-1 Bridge program keeps evolving, so it is good to keep an eye out for ongoing updates.

Senior looking at a smartphone showing an incoming call from an unknown number
By No author September 9, 2026
Medicare scam calls and fake insurance agents are on the rise. Learn the warning signs, how to verify who you're talking to, and what to do if you share information.
Older person's hands typing on a laptop keyboard indoors
By No author September 2, 2026
Annual Enrollment for Medicare runs October 15 – December 7, 2026. Here's what to know about comparing plans, key dates, and how to get ready.
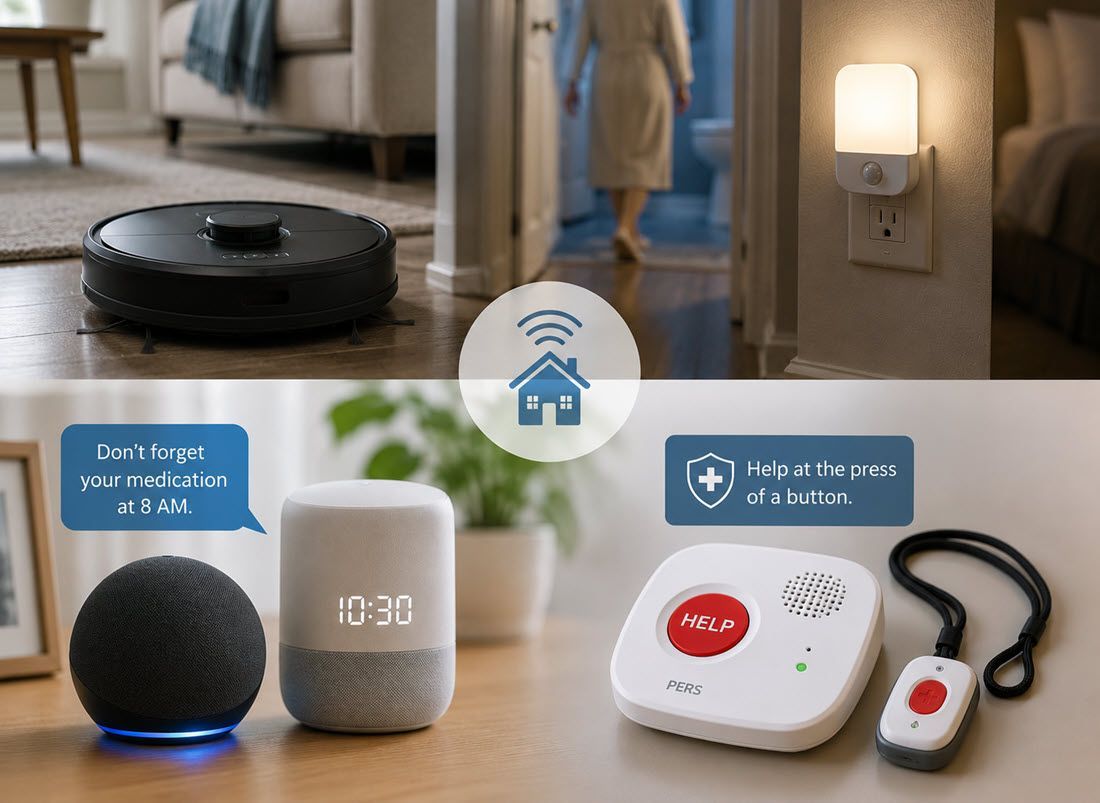
Smart home devices: robot vacuum, voice speaker, smart button, and emergency pendant in a hallway.
July 16, 2026
See how smart lighting, robot vacuums, stove shut-offs, medication reminders, and fall monitors can help seniors at home, plus what Medicare and Medigap do and do not cover.
Smiling person in a white hat outdoors, with a hand raised near the brim.
July 16, 2026
Learn what Medicare covers for skin cancer screenings, dermatologist visits, biopsies, and treatment, plus tips for prevention and early detection.
Two blue aluminum drink cans viewed from above, with water droplets on the lids.
By Agency Bloc September 24, 2025
As the summer sun beckons and thirst levels rise, it's tempting to reach for a cold, fizzy beverage. But before you pop open that soda can, consider this: your drink choice has long-term implications for your health. The Hidden Risks in Your Glass A comprehensive study by the International Agency for Research on Cancer (IARC) analyzed data from over 451,000 individuals across 10 European countries over a 16-year period. The findings revealed that consuming two or more 250 ml glasses of soft drinks daily—whether sugar-sweetened or artificially sweetened—was associated with a higher risk of all-cause mortality compared to those who drank less than one glass per month. Delving deeper: Artificially Sweetened Beverages : Individuals consuming two or more glasses daily had a 26% higher risk of death compared to those who consumed less than one glass per month. Specifically, there was a 52% increased risk of death from circulatory diseases. Sugar-Sweetened Beverages : Those consuming one or more glasses daily faced a 59% higher risk of death from digestive diseases. All Soft Drinks : A notable association was found between soft drink consumption and increased mortality from Parkinson's disease. Alternatives That Aren’t Any Healthier Think fruit juice or energy drinks are a safer bet? A study involving 13,440 U.S. adults aged 45 and older found that each additional 12-ounce serving of sugary beverages, including 100% fruit juice, was linked to an 11% higher risk of all-cause mortality. Specifically, each additional 12-ounce serving of fruit juice was associated with a 24% increased risk. Watch the sugar content of iced coffee beverages and alcoholic cocktails as well. Lifestyle Factors Matter, Too It's essential to note that high soft drink consumption often correlates with other unhealthy lifestyle choices. The IARC study observed that individuals who drank more soft drinks typically had higher body mass indexes and were more likely to smoke. Even after adjusting for factors like diet, physical activity, smoking, and education, the association between soft drink consumption and increased mortality risk remained significant. Refreshing Alternatives for the Season Looking to quench your thirst without compromising your health? Here are some delightful, healthier options: Infused Water : Add slices of citrus fruits, cucumbers, or berries to your water for a refreshing twist. Herbal Iced Teas : Brew teas like hibiscus or mint, chill them, and enjoy over ice. Sparkling Water with a Splash : Mix sparkling water with a splash of 100% fruit juice for a fizzy treat. Homemade Lemonade : Use fresh lemons, water, and a touch of natural sweetener like honey or stevia. Coconut Water : A natural source of electrolytes, perfect for rehydration. Final Thoughts Summer is a time for relaxation and enjoyment. By making informed beverage choices, you can savor the season while prioritizing your health. So, the next time you're reaching for a drink to beat the heat, consider these healthier alternatives. Your body will thank you!
Three travelers walking through a bright airport corridor with rolling suitcases
By Agency Bloc September 24, 2025
Whether you’re planning a weekend getaway or a long-awaited international adventure, setting off on a trip is always exciting—but can also be unpredictable. That’s why preparing for the unexpected, especially when it comes to your health, is essential. Knowing what your medical coverage includes (and doesn’t) while traveling can help you stay healthy, avoid costly surprises, and soak up the unforgettable moments on your journey. Let’s walk through some proactive steps you can take before packing your bags—from vaccinations and insurance to emergency planning and fraud protection. 1. Know What Your Health Plan Covers—And Where Medical surprises aren’t on anyone’s itinerary—but it’s best to be prepared. Start by knowing how your insurance policy covers (or doesn’t) the region you’re traveling to. Individual health policyholders, review your insurer’s network coverage. Some plans only cover in-network or state-specific services, while others offer broader emergency coverage or travel-specific riders. Consult your insurance agent to get help reviewing your policy. Medicare beneficiaries, Original Medicare (Parts A & B) typically doesn’t cover medical care outside the U.S., except in limited circumstances. If you have a Medicare Advantage Plan, it may include emergency and urgent coverage abroad, but this varies by provider. Check your plan’s Evidence of Coverage or speak to your plan representative before traveling. 2. Consider Supplemental Insurance If you're a frequent traveler or heading abroad, look into some options to help cover you. Some options include: Travel Medical Insurance : Plans offer emergency coverage during trips outside the U.S. and tend to be affordable. Evacuation Insurance : This covers transport to a qualified medical facility if the nearest care is inadequate. An evacuation clause is often, but not always, included in a travel insurance plan. Medicare Supplement Insurance (Medigap) : Some Medigap policies cover emergency care abroad, typically up to plan limits and with a deductible. Critical Illness Insurance : A lump-sum payout can provide financial flexibility in case you’re diagnosed with a covered condition like a heart attack or stroke during travel. Be sure to read the fine print—some policies require you to be under a certain age, and preexisting conditions may not be covered. Your licensed insurance agent can help talk you through your options. 3. Keep Your Medical Info Handy Consider using a secure health app or digital wallet to access all your health records quickly. But just in case your phone is inaccessible, bring physical copies of these important documents as well: Your insurance or Medicare cards Emergency contact numbers (include the country code +1 if you’re traveling abroad) A medication list with dosages Allergy and medical condition alerts Pack all essential paperwork together in a waterproof sleeve in your luggage, and leave a second copy with someone back home. 4. Schedule Preventive Care Before Departure Most insurance plans cover preventive care services like wellness visits, vaccinations, and screenings. Before your trip, check these tasks off your list: Get vaccinated : Make sure you’re up to date on your flu, COVID-19, and tetanus shots. If traveling internationally, check the CDC recommendations for the region you’re visiting, which may include Hepatitis A/B, typhoid, or yellow fever vaccinations.
SHOW MORE